What is the market overview of the Musical Instruments Market?
Our analysis indicates that the Musical Instruments Market represents a dynamic global ecosystem encompassing acoustic, electronic, and traditional gear. Valued at 17.45 Billion in 2026, the industry is underpinned by complex supply chains sourcing rare tonewoods and specialized electronic components, driven by cultural institutions, educational programs, and professional recording studios worldwide.
Key market drivers, restraints, challenges, and opportunities shaping the Musical Instruments Market
Growth is propelled by rising disposable incomes and digital integration, while strict CITES regulations on endangered tonewoods like rosewood act as notable supply restraints. Opportunities abound in the e-commerce expansion of specialty stores, allowing brands like Yamaha Corporation and Fender Musical Instruments Corporation to capture direct-to-consumer demand across emerging markets.
Emerging trends and growth patterns in the Musical Instruments Market
The shift toward hybrid setups—merging acoustic drums and pianos with digital sound modules—is transforming the Musical Instruments Market industry trends landscape. Innovations by Roland Corporation and Medeli Electronics (Shanghai) Co., Ltd. highlight how modern consumers demand portable, software-integrated gear for home-based music production and live streaming.
COVID-19 impact analysis and recovery trajectory
Pandemic-era lockdowns initially strained logistics through major maritime hubs, yet the Musical Instruments Market experienced a historic surge in personal use applications as locked-down consumers sought creative outlets. This consumption wave accelerated digital sales channels, establishing a resilient baseline that supported subsequent manufacturing recoveries across global factories.
Competitive benchmarking and strategic dynamics
Market concentration features a mix of heritage artisans and electronics giants. Firms like Steinway Musical Instruments Inc. and C.F. Martin & Co., Inc. rely on brand heritage and craftsmanship, whereas Casio Computer Co., Ltd. and Gibson Brands Inc. leverage aggressive patent portfolios and digital ecosystems to outmaneuver regional competitors.
Executive summary of the Musical Instruments Market
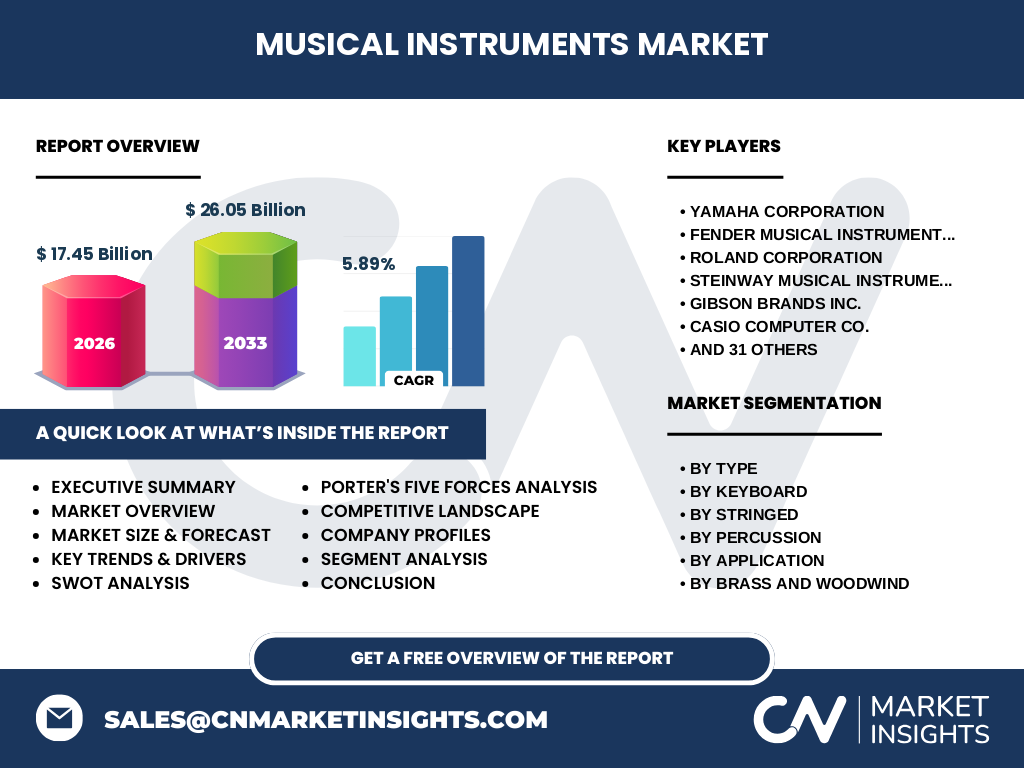
The Musical Instruments Market is poised for robust expansion, scaling from 17.45 Billion in 2026 to reach 26.05 Billion by 2033 at a CAGR of 5.89%. Strategic investments in electronic hybrids and localized distribution will dictate market leadership through the forecast period.
Market forecast from 2027 to 2033
Driven by accelerating demand in commercial events and personal use sectors, our projections show the Musical Instruments Market market size expanding steadily to hit 26.05 Billion by 2033. This trajectory translates to a steady 5.89% CAGR, rewarding manufacturers who optimize their online sales channels.
Segmentation analysis across product categories
The industry divides into distinct categories with unique supply chain demands:
- By Type: Stringed, Brass And Woodwind, Percussion, and Keyboard.
- By Keyboard: Pianos (Acoustic and Digital), Organs, Synthesizers, Keyboards, and Accordions.
- By Stringed: Guitars (Acoustic and Electric), Violins, Cellos, Harps, and Banjos.
- By Percussion: Drums (Acoustic and Electronic), Tambourines, Marimbas, Xylophones, and Bongos.
- By Brass And Woodwind: Trumpets, Trombones, Saxophones, Flutes, and Clarinets.
- By Application: Commercial Events, Personal Use, Music Production, and Other Applications.
- By Distribution Channel: Supermarkets Or Hypermarkets, Specialty Stores, and Online Sales Channel.
Regional market analysis and geographic distribution
Geographic performance hinges on regional arts funding and retail infrastructure. North America and Europe dominate mature segments like premium electric guitars and acoustic pianos, while Asia-Pacific acts as the primary manufacturing engine—anchored by facilities in China and Japan—while also showing the fastest consumption growth.
In-depth regional review of key growth zones
Asia-Pacific manufacturing powerhouses, including Guangzhou Pearl River Piano Group Co., Ltd. and Hoshino Gakki Co., Ltd., leverage proximity to raw material supplies. Meanwhile, Western markets drive high-margin replacement demand through specialty stores, prioritizing premium craftsmanship from makers like Eastman Music Company.
Company profiles and strategic positioning
Industry leaders command distinct market niches. Yamaha Corporation dominates multi-category manufacturing, while Avedis Zildjian Company focuses on specialized percussion components. Regional specialists like Strunal Schönbach s.r.o. and Zhangqiu Tongxiang Musical Instrument Factory provide essential B2B manufacturing depth, balancing global brands with localized expertise.
Porter's Five Forces analysis of the industry
Rivalry is intense among established brands like Gibson Brands Inc. and Fender Musical Instruments Corporation, while the threat of new entrants remains moderate due to high capital requirements for precision woodworking and acoustic engineering. Buyer power is mitigated by brand loyalty, though online price transparency exerts constant margin pressure.
SWOT analysis for strategic market planning
Key strengths include deep brand equity and generational artisan skills. Weaknesses involve vulnerability to lumber supply disruptions. Opportunities lie in digital learning integrations, while threats include macroeconomic downturns impacting discretionary spending on commercial events and personal hobbies.
Value chain analysis from raw materials to end-users
The value chain starts with ethical timber harvesting and rare metal sourcing, moving through precision machining facilities run by firms like Tianjin Leo Musical Instruments Co., Ltd. and Jiyi Musical Instruments Co., Ltd. Finished goods flow through global shipping ports to specialty stores and online channels for end-users.
Investment insights and high-potential areas
Investors should target electronic percussion and synthesis innovators, particularly companies supplying software-integrated gear for home studios. Brands partnering with online educational platforms are best positioned to capture recurring revenue streams within the expanding personal use segment.
Conclusion and key takeaways
The Musical Instruments Market analysis confirms a resilient, growing sector projected to reach 26.05 Billion by 2033. Success relies on balancing traditional acoustic craftsmanship with agile digital distribution strategies and eco-friendly material sourcing.
Research methodology behind our market estimates
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with executives from John Packer Ltd. and Aria Guitars Co., and secondary macroeconomic indicators tracking consumer discretionary spending across major industrialized economies.
Scope of the report and coverage parameters
This comprehensive Musical Instruments Market report evaluates global revenues from 2026 to 2033. Coverage parameters exclude custom, one-off orchestral builds, focusing instead on mass-produced commercial categories across all major distribution channels and geographic regions.
Recent developments in the industry
Recent strategic moves feature aggressive digital product launches and cross-border partnerships. Companies like Wuhan Eleca Electronics Co., Ltd. and Shenzhen Gmax Musical Instrument Ltd. have scaled their OEM operations to supply booming online sales channels with affordable, high-specification electronic gear.